Insights into ASX Stocks
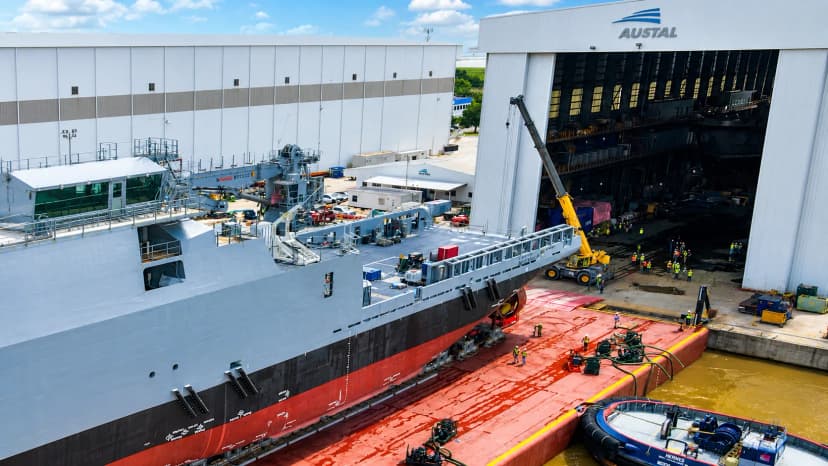
Austal (ASX: ABS): Breaks Downtrend with Defence Contracts in Focus
Austal (ASX: ASB) gains investor attention after Hanwha’s proposal for Austal USA, alongside major defence contracts and a technical breakout. The company faces both strategic opportunities and execution risks as its shipbuilding plans evolve.
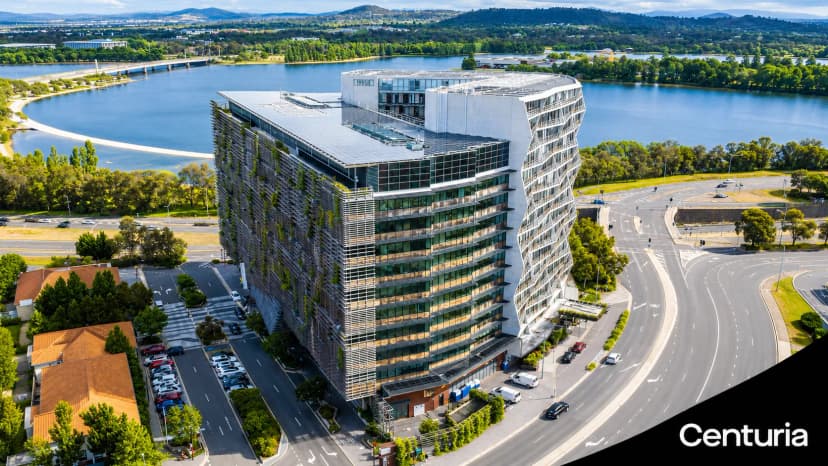
Centuria Office REIT (ASX: COF): Earnings Hold Firm, but Sellers Still Control the Trend
Centuria Office REIT is improving leasing, refinancing debt and stabilising property values, but lower FY27 distributions and high gearing remain concerns. COF now sits near key support as investors weigh stronger operations against lingering office market risks.
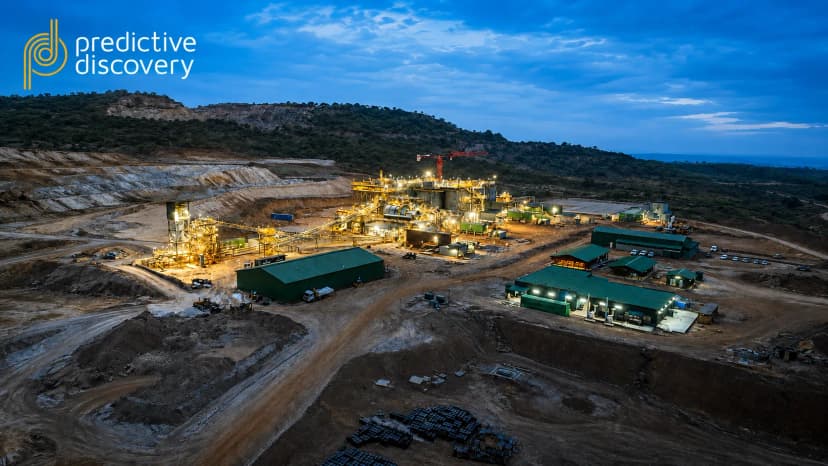
Predictive Discovery (ASX: PDI): Strong Gold Output and Cash Growth Drive the Price Toward Resistance
Predictive Discovery has become a cash-generating West African gold producer following its Robex merger. Strong June output, rising cash reserves, Bankan engineering progress and regional expansion are strengthening its growth case, though permitting, cost and execution risks remain.
Steadfast Group (ASX: SDF): Margin Growth and Global Expansion Through Cycle Resilience
Steadfast Group (ASX: SDF) delivers double‑digit EBITA growth, disciplined acquisitions, and margin expansion across Australasian and international operations, reinforcing its status as a resilient blue‑chip compounder.
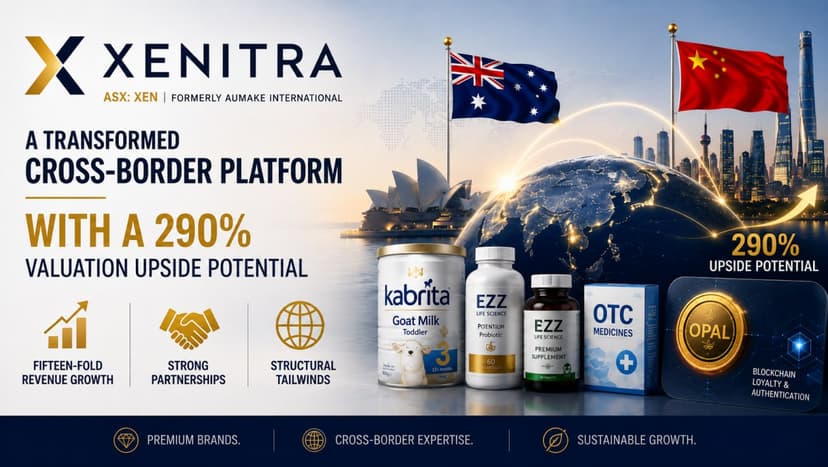
Xenitra, ASX: XEN (formerly AuMake International): A Transformed Cross-Border Platform with a 290% Valuation Upside Potential
Xenitra (ASX: XEN) has transformed from a tourism-dependent retailer into a diversified cross-border platform connecting Australian and New Zealand health and consumer brands with Greater China. Revenue has grown roughly 15-fold from A$2.7m in FY23 to A$39.8m in FY25, while the company remains valued at only ~0.3x FY25 sales. With growth across nutritionals, OTC medicines and its OPAL platform, supported by major partnerships and favourable Chinese market tailwinds, Xenitra appears positioned for significant margin and earnings growth. A DCF valuation of A$0.0096–A$0.0137 per share implies substantial upside from the current A$0.003 share price.
Benz Mining Corp. (ASX: BNZ): District‑Scale Gold Momentum and Structural Upside
Benz Mining Corp (ASX: BNZ) advances its Glenburgh Gold Project toward resource definition, delivering high‑grade intercepts, strong funding, and district‑scale potential that positions it as one of Australia’s most aggressive gold growth stories.