
Beach Energy (ASX: BPT): Undervalued Gas Producer with Growth Potential
Beach Energy is a gas-focused Australian producer supplying the domestic east coast market, with most output coming from the Cooper, Otway and Perth basins. The key growth driver is the Waitsia Gas Project, which could lift production and cash flow as it ramps up. The stock offers a high fully franked dividend but remains sensitive to energy prices and project execution.
Mineral Resources (ASX: MIN): An undervalued ASX miner facing an important resistance level
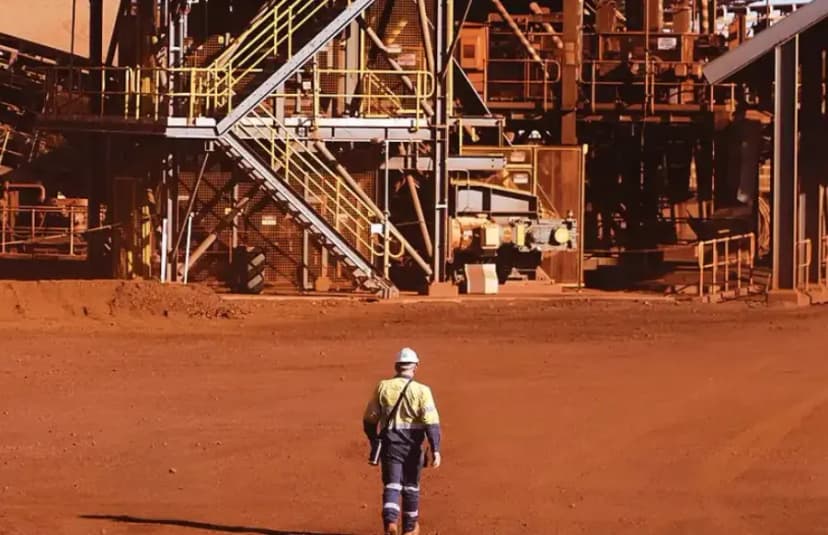
Mineral Resources is emerging from a heavy investment phase as the Onslow Iron project reaches scale, driving a sharp recovery in earnings and cash flow. With iron ore production ramped up and lithium assets backed by a major POSCO partnership, the business is now showing the financial benefits of years of expansion. Despite the turnaround, the stock still appears undervalued relative to its long‑term earnings, cash‑flow potential, and asset base.

Is it a good time to buy NRW Holdings (ASX: NWH) after the bounce off its major support level?
NRW Holdings is an Australian mining services contractor providing civil construction and contract mining to major producers like BHP and Rio Tinto. Its earnings are closely tied to Australia’s mining investment cycle. Strong cash flow and new contracts could support recovery if resource sector capex remains strong.

Is Qantas Airways (ASX: QAN) a buy opportunity after the recent drop or a falling knife?
Qantas (ASX: QAN) has pulled back sharply in 2026, but the decline is largely driven by cyclical pressures rather than a broken business. The key trigger has been a surge in jet fuel costs, which have more than doubled in recent months.

Why Cochlear's (ASX: COH) share price keeps crashing, and where can it find a bottom?
Cochlear’s share price slump reflects profit downgrades, slowing growth, weak global demand, and macro pressures. The stock is down sharply, but a lasting bottom likely depends on stabilising earnings and clearer signs of demand recovery.

CSL (ASX: CSL) Shares Sink After Massive Impairment Shock Hits Market Confidence
CSL shares crashed after a US$5 billion impairment warning and weaker guidance shocked investors, sending the stock below A$100. Despite strong long-term fundamentals in plasma therapies, technical indicators remain bearish with heavy selling pressure still dominating the chart.